Fintech
HL Hunt shows its work: three sample deals behind the “banks said no” pitch
A logistics company, a dental practice and an auto repair shop appear on HL Hunt’s site as recently funded examples. The page frames the product as capital for businesses banks turn down — the company’s words, not an audited track record.
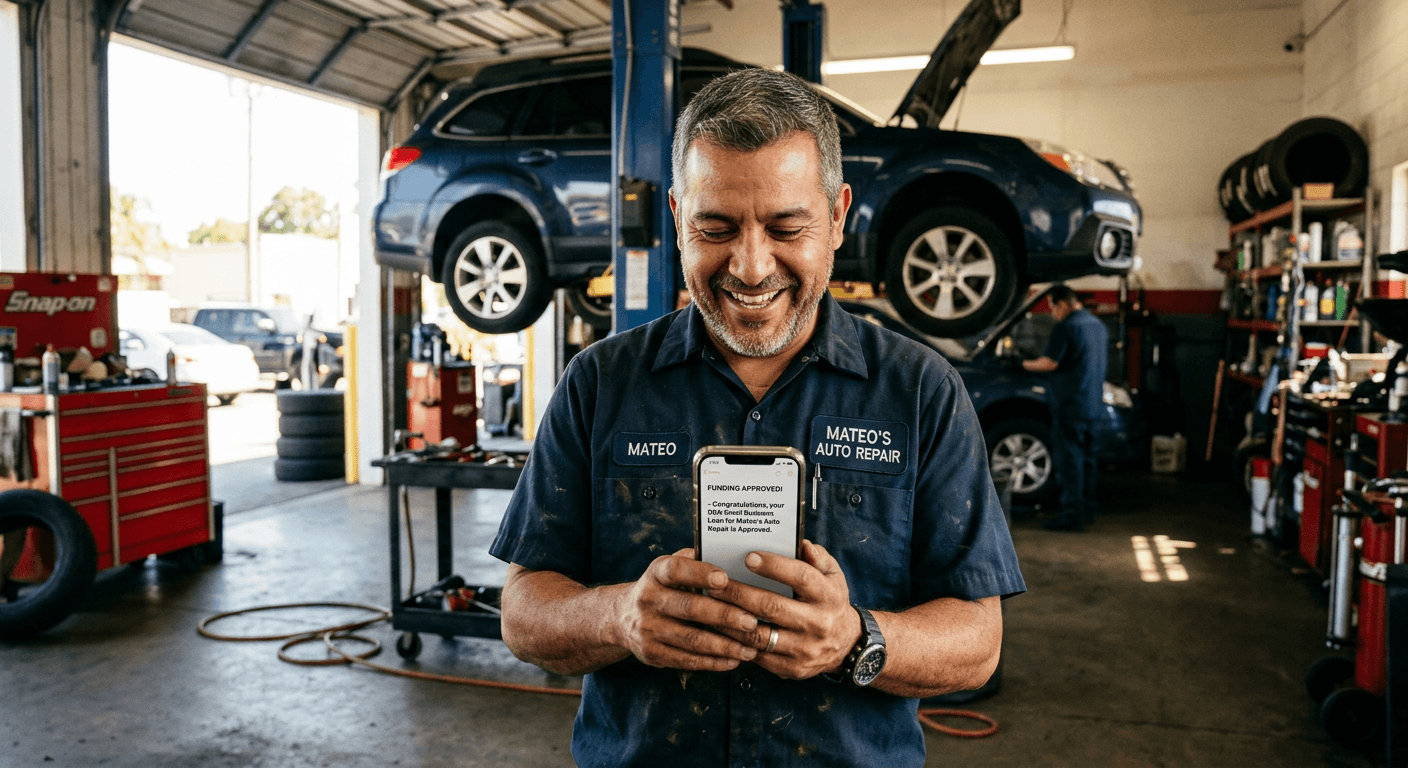
HL Hunt Financial’s Business Funding page leads with a small showcase of named example deals rather than only product descriptions: a merchant cash advance of $120,000 to a logistics company, an $85,000 invoice-factoring approval for a dental practice, and a $60,000 business line of credit for an auto repair shop, each tagged "Funded" or "Approved." It is the kind of social-proof display common across small-business lending marketing, and it sits alongside the company’s aggregate claims — more than $250 million funded to businesses, a 24-hour average time to fund, a 90%-plus approval rate, and funding available up to $5 million.
The page’s core pitch, in the company’s own language, is that "HL Hunt funds businesses banks turn down" because traditional lenders "take weeks, demand collateral, and want perfect credit," while HL Hunt says it looks at "real revenue" and funds in days. That framing is standard positioning in the alternative small-business lending space, where merchant cash advances and factoring have grown precisely because bank underwriting timelines and collateral requirements exclude many applicants — but it is also framing, not a neutral description, and it is written to make the comparison as favorable as possible.
What is not present on the page is independent verification of any of these figures. The three example deals are not accompanied by documentation, dates, or a way to confirm the businesses exist as described; the $250 million aggregate figure has no stated time period or audit source; and the 90%-plus approval rate — a notably high figure for alternative small-business financing — is not broken out by product type, applicant profile, or compared against a defined denominator of total applications received. These are the kind of numbers a reasonable reader should treat as marketing claims until a company publishes underlying data or a third party verifies them.
This is also where the product’s brokerage structure, previously covered on this site, matters for interpreting the stats: HL Hunt says it connects businesses to funding partners rather than lending its own balance sheet on most products, so a "90%-plus approval rate" plausibly reflects approval by any partner in the matching network rather than approval at any single, fixed set of terms. A business reading the showcase deals and aggregate stats should treat them as illustrative of the kind of deal HL Hunt says it can source, not as a guarantee of similar terms, timeline, or approval odds for any individual applicant.
As with HL Hunt’s other marketing pages covered here, the company’s claims may well be accurate — merchant cash advances and invoice factoring genuinely do serve businesses that banks decline, and 24-to-48-hour funding timelines are realistic for those product types. The point of this coverage is narrower: none of the specific figures on the page are independently verified, and a business evaluating the product should ask for current approval-rate data and underwriting criteria directly rather than relying on the marketing page’s aggregate statistics alone.
Company material cited
- HL Hunt Business Funding page — recently funded examples and aggregate statistics — Named example deals, funding totals, average time to fund, and approval-rate claims as published by the company