Fintech
HL Hunt’s Personal Credit Builder sells a primary tradeline, not cash access
The five-tier membership reports a revolving account to Experian, Equifax and TransUnion, while restricting actual spending to HL Hunt’s own marketplace.
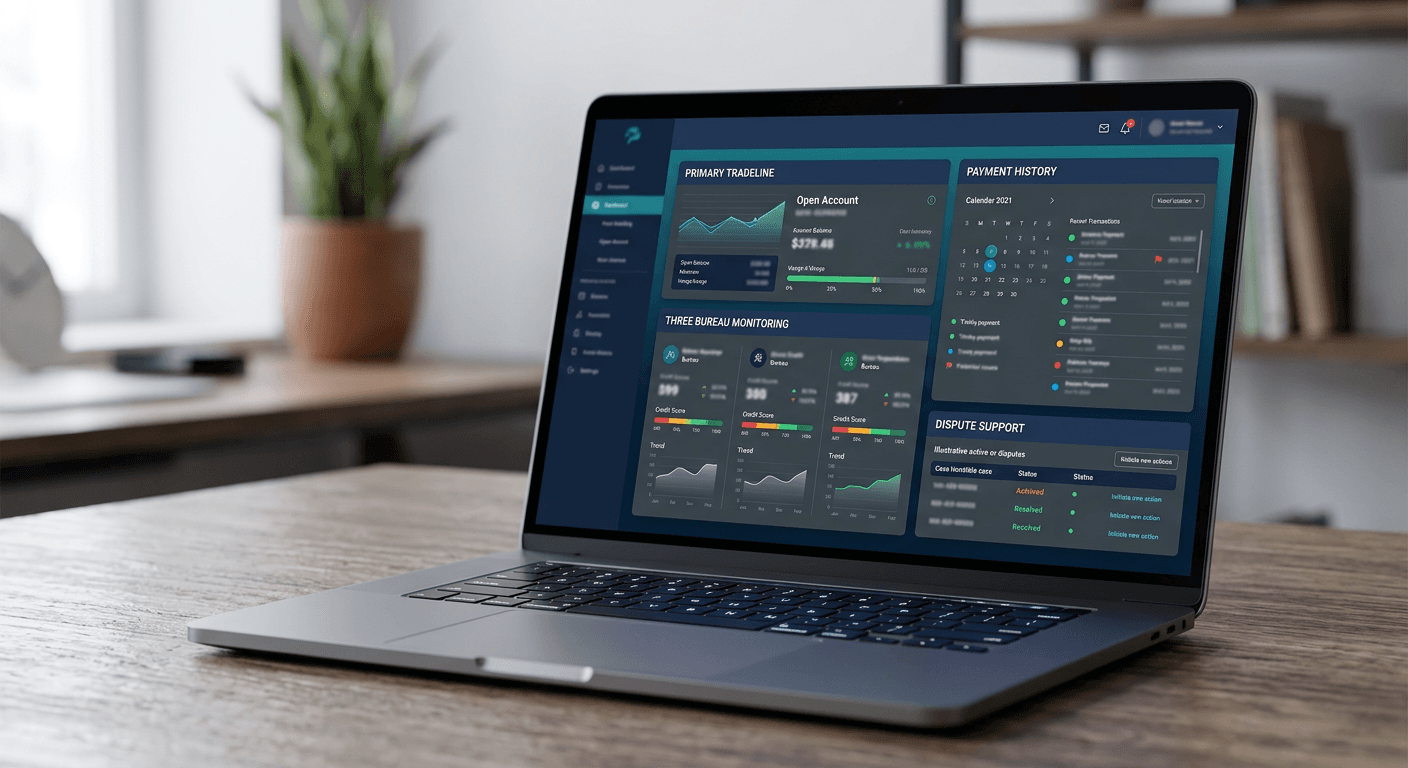
HL Hunt Financial’s Personal Credit Builder is built around a primary-tradeline model. Instead of adding a consumer as an authorized user on an existing account, the company says it opens a new revolving account in the member’s own name and reports the account each month to Experian, Equifax and TransUnion.
The product has five membership tiers. The Basic plan is listed at $9.99 per month for a $1,000 reported limit, while the top Platinum plan is $99.99 per month for a $10,000 reported limit. The company says every tier carries a 0% APR and includes credit monitoring, a net-worth dashboard and dispute support. The monthly fee is therefore the principal cost shown on the product page, although consumers should review all terms before enrolling.
The most important limitation is how the credit can be used. HL Hunt says members can use the line only within its own marketplace of financial tools, services and everyday products. It is not a cash advance, general-purpose card or unrestricted line for bills and purchases elsewhere. That closed-loop design may limit the company’s exposure, but it also means the reported limit is not equivalent to liquid credit available to the member.
HL Hunt says no credit check is required. That may make the product accessible to consumers with thin or damaged files, but reporting an account does not guarantee a higher score. Results depend on whether the bureaus accept and match the data, how utilization and payment history are calculated, what other accounts appear in the file, and whether the member remains enrolled long enough for age and payment history to matter.
The product’s value proposition is consequently narrow and specific: it offers a paid way to establish a new reported account, with marketplace-only usage and monitoring tools. A consumer should ask for the full agreement, reporting policy, cancellation consequences, dispute procedure and any conditions attached to the 0% APR claim before treating it as a substitute for conventional credit or a guarantee of score improvement.
Company material cited
- HL Hunt Personal Credit Builder page — Five tiers, monthly pricing, reported limits, bureau coverage, marketplace restriction and company product claims